Preventing Chargebacks With Better Customer Support
By HighRiskPay Editorial Team · Updated 2026-08-20
Responsive refund policies and documented customer support communication reduce chargeback risk substantially. Global chargeback volume varies; contact the brand directly for the latest figures. HighRiskPay structures high risk merchant accounts with real-time transaction monitoring, Chargeback Management & Dispute Workflow, and rule-based filters, giving compliance teams the tools to resolve
The Economic Impact of Chargebacks on High-Risk Merchants
- Global chargeback volume reached $117 billion by end of 2023, threatening business profitability significantly.
- Chargebacks cost merchants the sale price plus additional fees and monthly fines from card networks.
- Refunds process faster than chargebacks and avoid the financial penalties associated with dispute resolution.
- Proactive prevention strategies and understanding chargeback processes reduce risk and protect business revenue effectively.
Why Do Refunds And Chargebacks Threaten High-Risk Merchants?
Refunds and chargebacks drain revenue faster than most operators realize, and they threaten reputation and banking relationships along with it. Global chargeback volume varies. Contact the brand directly for the latest figures, a reality that turns dispute management into a core business priority rather than a back-office task. High-risk merchants absorb this pressure differently than standard retailers because mainstream payment infrastructure was never built for them.
Conventional payment providers assume predictable, low-risk transaction patterns. Businesses in adult content, nutraceuticals, forex, or subscription models rarely fit that mold. When transaction behavior falls outside those narrow parameters, merchants face declined applications, sudden account freezes, and processing limits that choke growth.
Why do standard providers struggle with high-risk dispute exposure?
Standard acquirers are not designed to absorb elevated dispute volume. That mismatch leaves legitimate businesses exposed to instability just when consistent processing matters most.
What happens when chargeback exposure goes unmanaged?
Unmanaged exposure compounds. Rising chargeback ratios raise scrutiny from acquiring banks, invite penalties, and eventually put merchant accounts at risk of termination.
For risk and compliance teams, the stakes break down clearly:
- Revenue loss from reversed transactions and lost merchandise
- Banking instability when providers lack tools for elevated-risk verticals
- Compounding exposure as unresolved disputes accumulate over time
Structured chargeback avoidance, responsive customer support, and a transparent refund policy form the foundation for withstanding this pressure.
How Does A Clear Refund Policy Reduce Disputes?
A documented refund policy shortens the path between a customer complaint. A resolution, keeping frustrated buyers away from their bank. Confusion drives disputes; clarity prevents them. When cardholders know exactly what to expect, they contact the merchant first instead of filing a claim with their card issuer.
Billing clarity plays a direct role here. Recognizable, easy-to-read transaction descriptors are among the simplest and least expensive prevention measures a business can adopt. Unfamiliar charges are a leading trigger for cardholder confusion and chargeback filings.
Merchants operating in regulated or high-risk categories need infrastructure that supports this kind of clarity at scale. Offshore High-Risk Accounts: Top Jurisdictions for Company Formation built with enterprise-grade fraud and chargeback avoidance tools give operations teams the systems needed to catch and resolve refund requests before they escalate into formal disputes. Payment structures built specifically for high-risk business models, rather than retrofitted from low-risk platforms, create the operational stability required for consistent, predictable refund handling across order volume and geography.
Why does refund clarity matter financially?
Every unresolved refund request carries a real cost. Chargebacks bring lost merchandise, processing fees, and administrative overhead on top of the original sale.
What should a strong refund policy include?
- Clear timeframes for requesting refunds
- Plain-language eligibility criteria
- Visible customer support contact channels
- Consistent enforcement across all sales channels
What Tools Support Chargeback Avoidance And Customer Support?
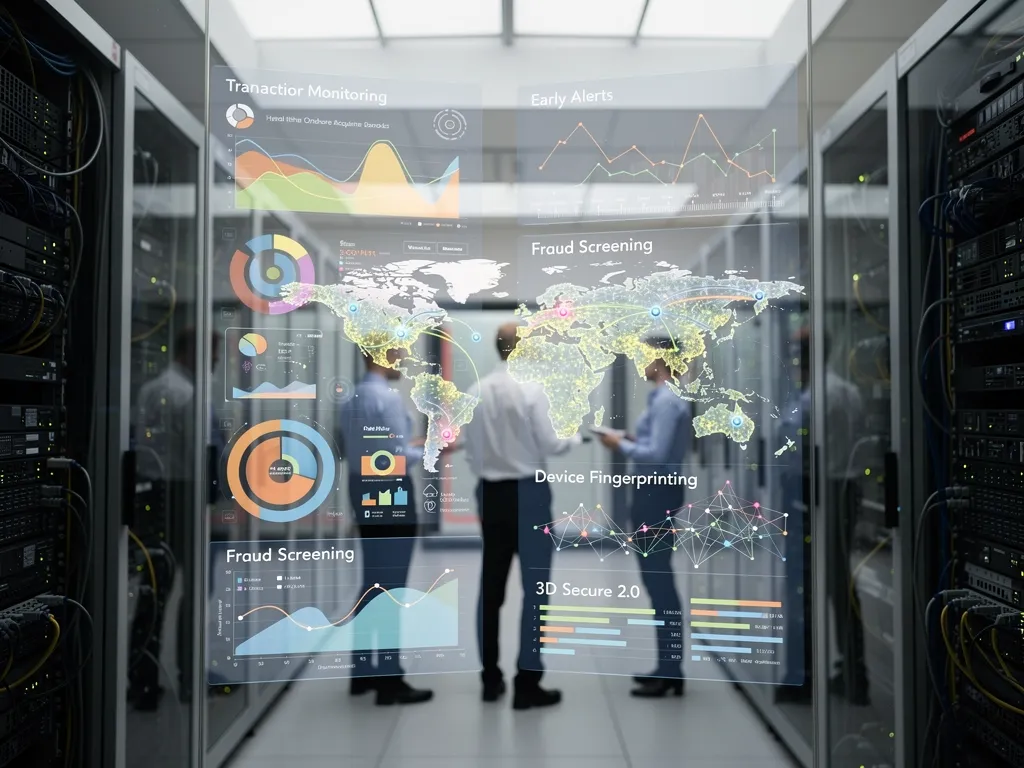
Five layered technologies form the backbone of dispute prevention: real-time transaction monitoring, early dispute alerts, fraud screening, device fingerprinting, and 3D Secure 2.0. Merchant teams gain visibility into suspicious activity before disputes escalate into formal chargebacks. Combined, these tools catch fraud patterns that no single system detects alone.
Strong chargeback avoidance also depends on infrastructure, not just software. A network spanning more than 10 onshore. Offshore acquiring banks reduces dependence on any single processor when dispute volume spikes. Kyc Aml Highrisk: KYC AML High-Risk Account Compliance pairs with risk-aware structuring to improve approval rates and extend processing limits, helping merchants scale into new regions without losing continuity.
Which dispute type determines the right response?
Disputes generally fall into three categories: fraud, merchant error, or first-party misuse, sometimes called friendly fraud. Identifying the category first lets risk teams route each case to the correct fix and apply the right friendly fraud prevention response: fraud screening for stolen cards, clearer refund policy messaging for fulfillment errors, and responsive customer support for buyer confusion.
Why does acquiring bank diversity matter for support teams?
Relying on one acquirer leaves support and risk staff exposed if that bank tightens limits after a dispute spike. Multiple acquiring relationships keep processing running while teams resolve the underlying issue, protecting revenue during high-risk review periods.
FAQ
Why do refunds process faster than chargebacks?
<answer> Refunds process faster than chargebacks and avoid the financial penalties associated with dispute resolution. This makes them a more efficient path for resolving customer complaints than card network disputes. </answer>
What role does a clear refund policy play in preventing chargebacks?
<answer> A documented refund policy shortens the path between a customer complaint and a resolution, keeping frustrated buyers away from their bank. When cardholders know what to expect, they contact the merchant first instead of filing a dispute. </answer>
How do recognizable transaction descriptors help prevent chargebacks?
<answer> Recognizable, easy-to-read transaction descriptors are among the simplest and least expensive prevention measures a business can adopt, since unfamiliar charges are a leading trigger for cardholder confusion and chargeback filings. </answer>
Conclusion
In closing, effective refund management and responsive customer support form the foundation of chargeback prevention. By establishing clear policies, processing refunds promptly, and addressing customer concerns before disputes escalate, merchants substantially reduce the financial and operational burden of chargebacks. HighRiskPay’s integrated monitoring and dispute alert systems empower businesses to identify. Resolve issues proactively, transforming support into a strategic advantage that protects revenue and strengthens long-term processing stability.